Manufacturing Business Outlook Survey
November 2026 Report
Jump to
Summary of ReturnsView a PDF version of this report | View a TXT version of this report
Manufacturing activity in the region was less widespread but continued to expand overall, according to the firms responding to the November Manufacturing Business Outlook Survey. The survey’s indicator for general activity fell to a six-month low but remained positive. The new orders index fell to a near-zero reading, while the shipments index moved higher. The employment index rose, continuing to suggest overall gains in employment. Both price indexes increased from already elevated readings. Most future indicators declined this month but continued to suggest expectations for overall growth over the next six months.
Current Indicators Are Mixed
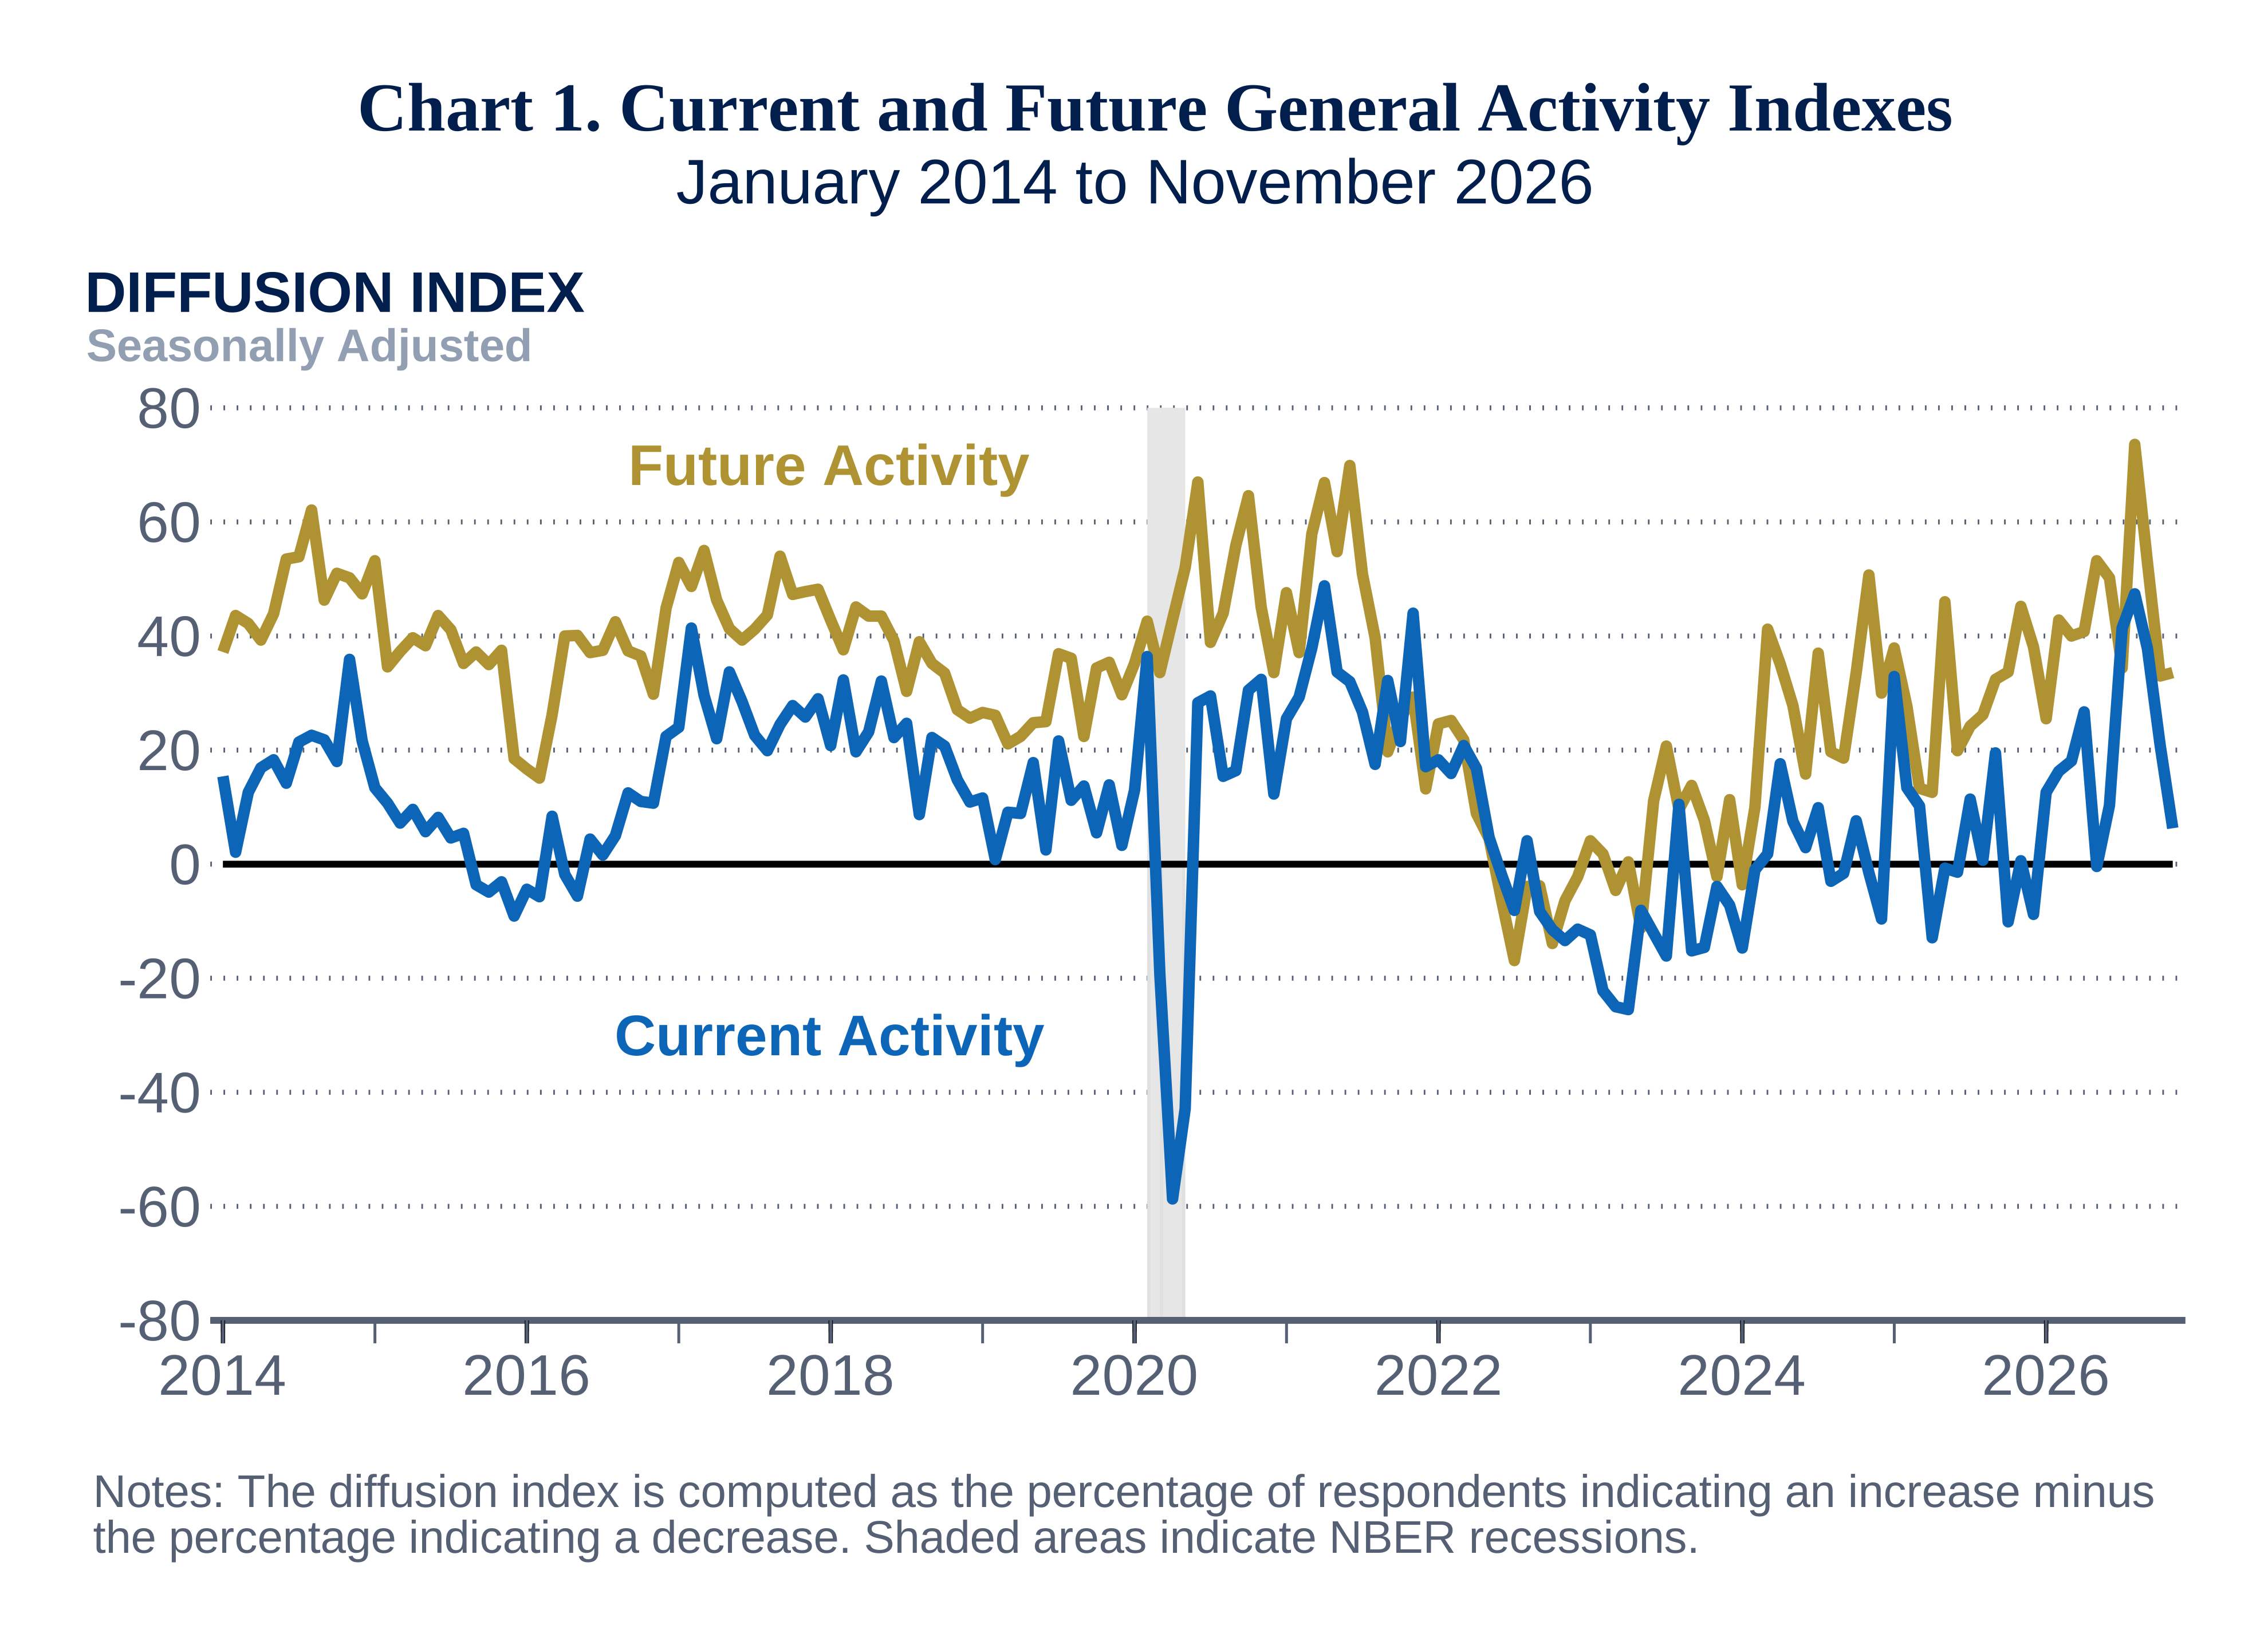
The diffusion index for current general activity fell from 20.9 in October to 6.3 in November, its lowest reading since May (see Chart 1). More than 36 percent of the firms reported increases in activity, while 30 percent reported decreases; 33 percent of the firms reported no change in activity. The current new orders index dropped 5 points to -0.4, its lowest reading since May and the index’s fourth consecutive decline. More than 32 percent of the firms reported decreases in new orders (down from 34 percent last month), while 32 percent reported increases (down from 39 percent); 35 percent reported no change (up from 22 percent). The shipments index rose 10 points to 25.7, offsetting most of the previous month’s decline.
The employment index rose 3 points to 11.6, its first increase in three months. More than 21 percent of the firms reported an increase in employment levels, 10 percent reported decreases, and 69 percent reported no change. The average workweek index rose from 7.5 to 11.2.
Price Indexes Remain Elevated
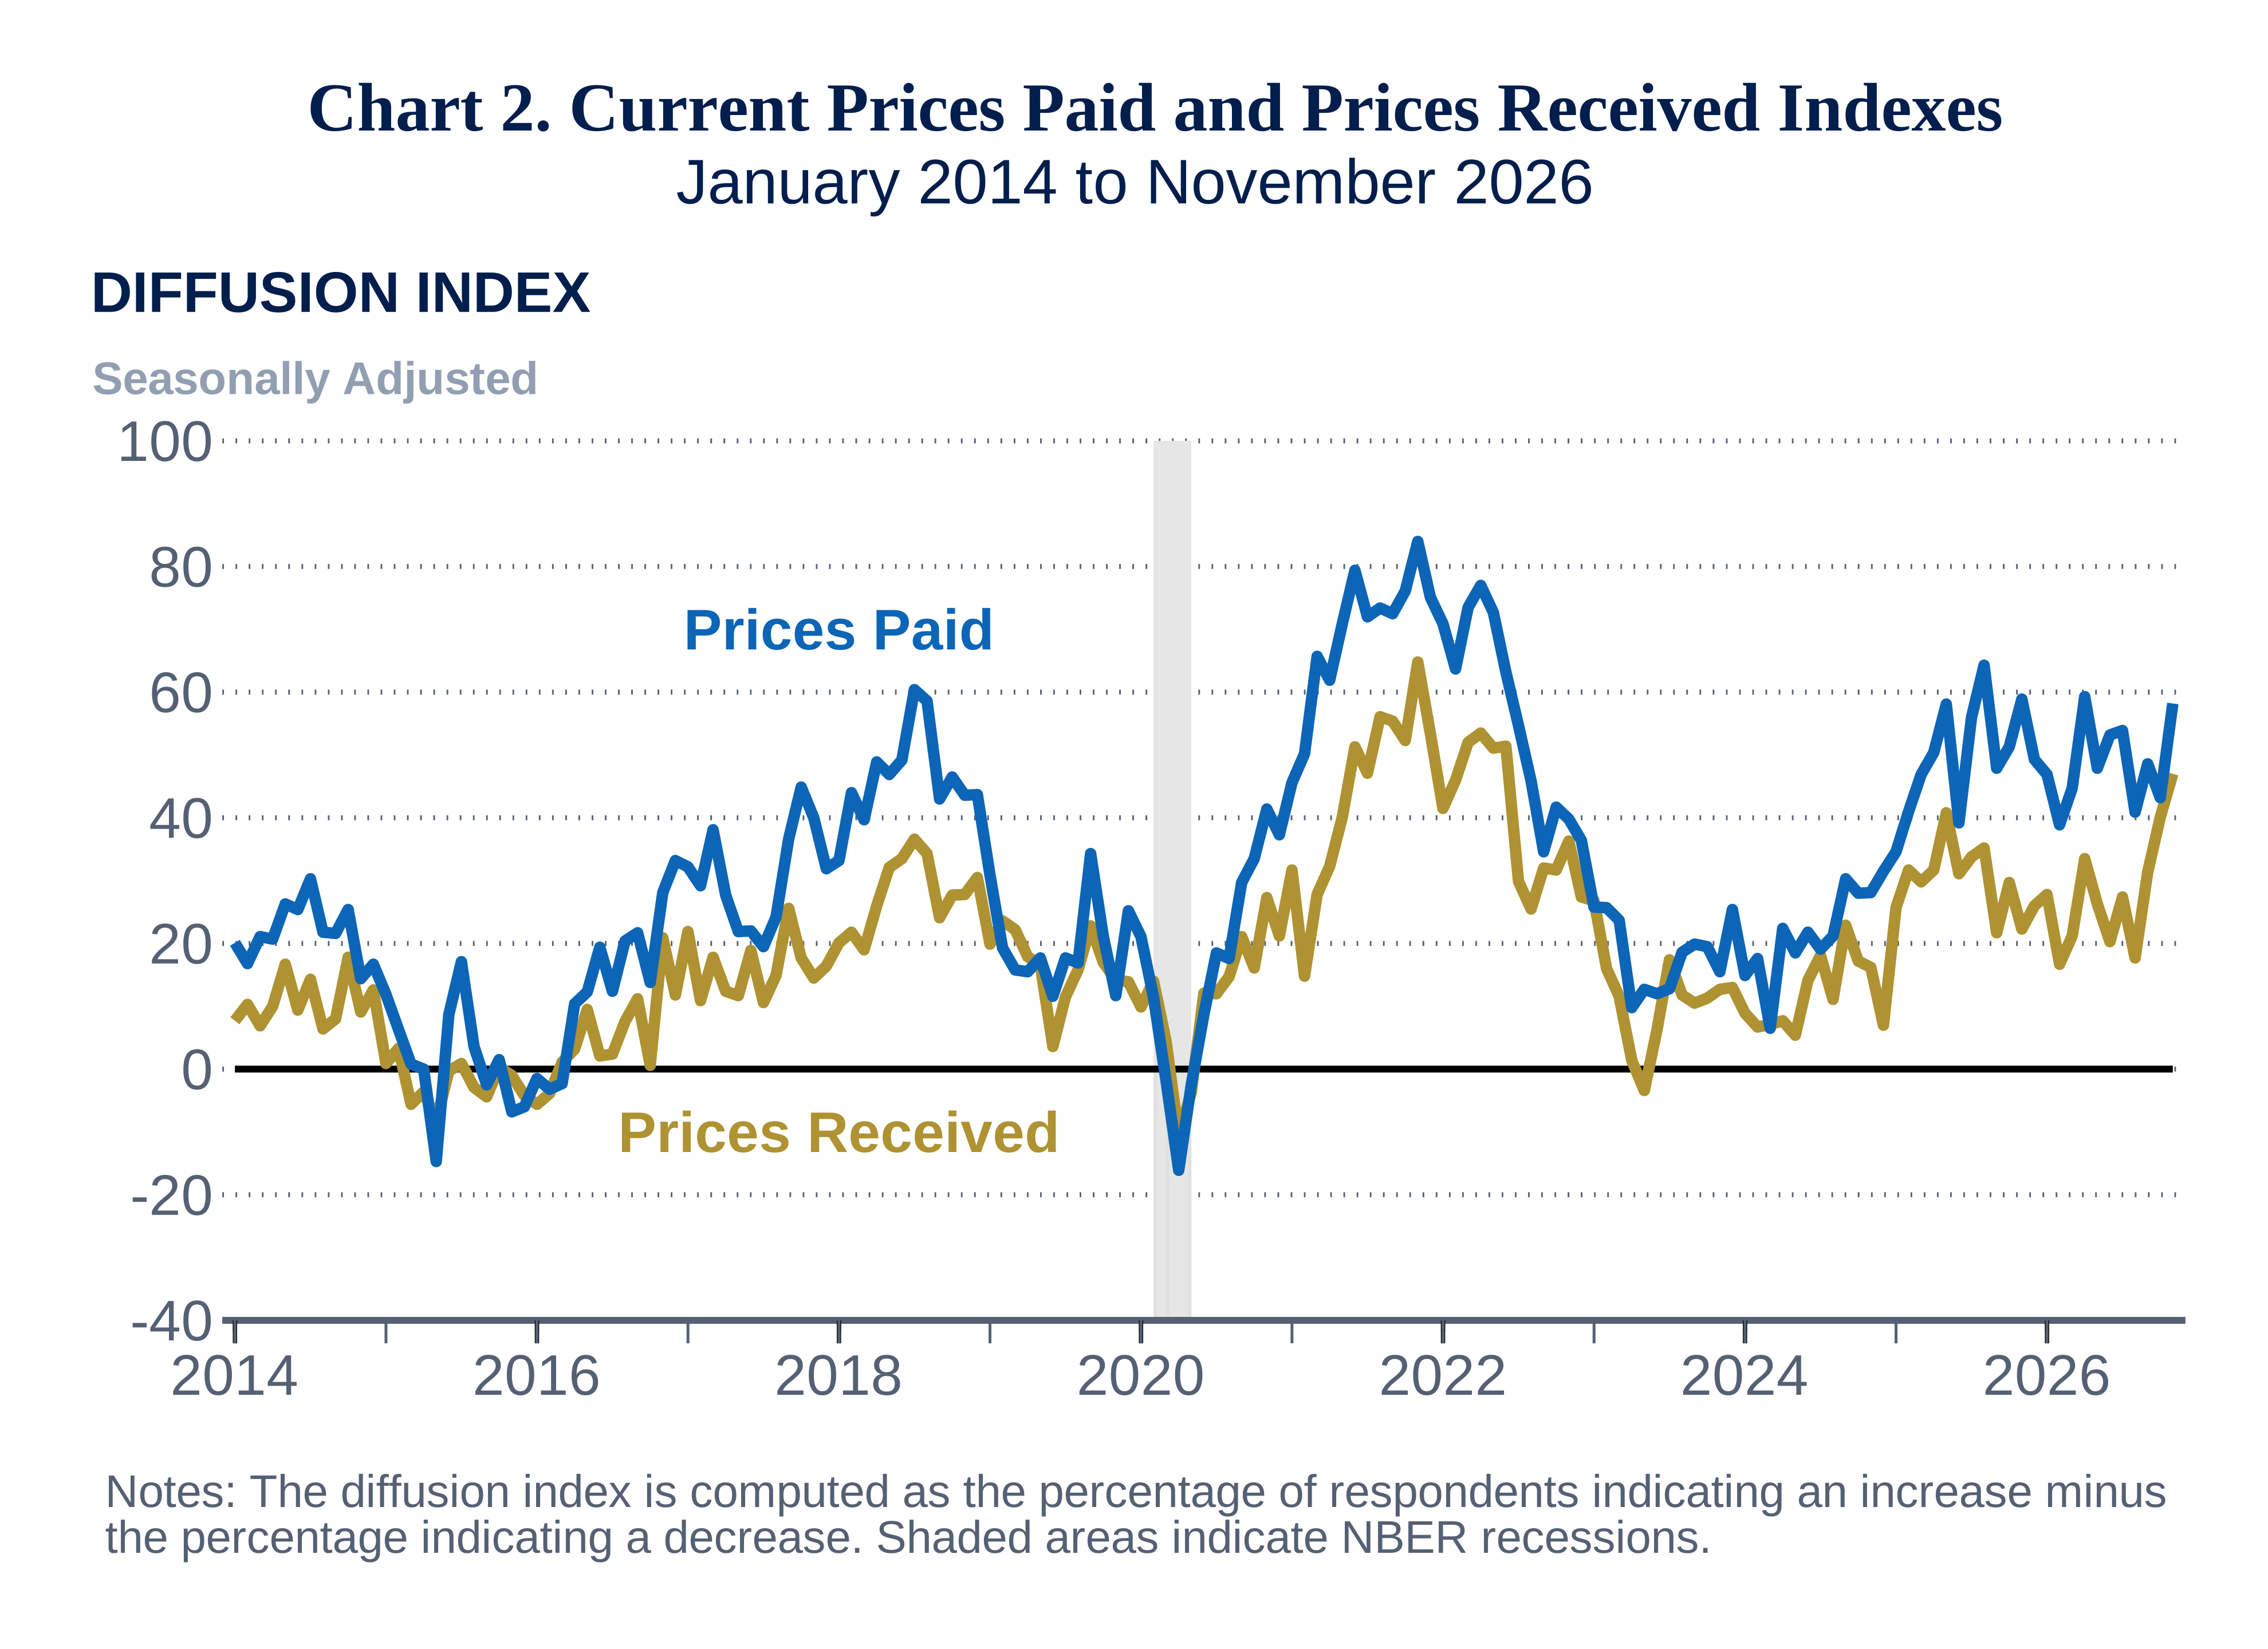
Both price indexes rose further above their long-run nonrecession averages in November. The prices paid index rose 15 points to 58.2, its highest reading since April (see Chart 2). More than 58 percent of the firms reported increases in input prices (up from 43 percent last month), while none reported decreases (unchanged); 39 percent reported no change in input prices (down from 52 percent). The current prices received index increased 7 points to 47.0, its highest reading since June 2022. More than 48 percent of the firms reported increases in the prices of their own goods, 1 percent reported decreases, and 51 percent reported no change.
More Than Half of the Firms Expect Near-Term Changes to Industry Costs
In this month’s special questions, manufacturers were asked about their plans for different categories of capital expenditures next year. More than 42 percent of the firms reported that customers have become more price sensitive since last quarter, while 54 percent reported customers’ sensitivity was about the same. Fifty-six percent of the firms indicated they anticipate changes in their industry’s costs in the near term (up from 44 percent last quarter), and 79 percent of those firms expect their competitors to raise prices in response. Regarding when these price changes will occur, the firms’ median expectation was for competitors to change prices in the next three months, down from four months last quarter.
Most Future Indicators Weaken
The diffusion index for future general activity was little changed at 33.6 this month, following two consecutive declines (see Chart 1). More than 50 percent of the firms expect an increase in activity over the next six months, and 17 percent expect a decrease; 23 percent expect no change. The future new orders index declined 5 points to 31.7, and the future shipments index fell 10 points to 25.4, each reaching its lowest reading in more than a year. The firms continue to expect increases in employment over the next six months, but the future employment index declined 5 points to 24.9, its lowest reading since February. Both future price indexes were little changed this month, well above their long-run averages. The future prices paid index edged up to 63.3, and the future prices received index ticked up 1 point to 62.9. The index for future capital expenditures fell 16 points to 18.9, its third consecutive decline and lowest reading since February.
Summary
Responses to the November Manufacturing Business Outlook Survey suggest that the region’s manufacturing activity continued to expand overall but was less widespread this month. The indicators for current activity and new orders declined to six-month lows, while the shipments index increased this month. The employment index rose, continuing to suggest overall gains in employment. Price increases were more widespread this month, and both price indexes remained well elevated. The survey’s broad indicators for future activity declined but continued to suggest expectations for growth over the next six months.
Special Questions (November 2026)
|
|
Percent (%) |
|---|---|
| More sensitive | 42.3 |
| About the same | 53.8 |
| Less sensitive | 3.8 |
| Don't know | 0.0 |
|
|
Percent (%) |
|---|---|
| Yes | 56.0 |
| No | 44.0 |
|
|
Percent (%) |
|---|---|
| Raise prices | 78.6 |
| Hold prices steady | 14.3 |
| Lower prices | 7.1 |
| Don't know | 0.0 |
| *Only firms that responded “yes” to question 2 responded to question 2a. |
|
|
Number of months |
|---|---|
| Median response | 3.0 |
| **Only firms that responded “raise prices” or “lower prices” to question 2a responded to question 2b. | |
MBOS Summary of Returns – November 2026
| November vs. October |
Six Months from Now vs. November |
|||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
|
Prev. Diff. Index |
Inc. | No ch. | Dec. |
Diff. Index |
Prev. Diff. Index |
Inc. | No ch. | Dec. | Diff. Index |
|||
| General Business Activity | 20.9 | 36.1 | 32.7 | 29.8 | 6.3 | 33.0 | 50.7 | 23.1 | 17.1 | 33.6 | ||
| New Orders | 4.3 | 31.7 | 35.4 | 32.1 | -0.4 | 37.0 | 49.3 | 24.7 | 17.7 | 31.7 | ||
| Shipments | 15.3 | 43.4 | 39.0 | 17.6 | 25.7 | 35.2 | 43.7 | 29.1 | 18.3 | 25.4 | ||
| Unfilled Orders | 2.4 | 23.2 | 46.0 | 27.5 | -4.4 | -1.6 | 24.7 | 51.8 | 15.6 | 9.1 | ||
| Delivery Times | 8.5 | 17.6 | 68.2 | 14.1 | 3.5 | -7.5 | 23.6 | 60.2 | 9.1 | 14.5 | ||
| Inventories | -12.8 | 19.2 | 59.0 | 13.9 | 5.3 | 23.4 | 36.0 | 36.5 | 17.6 | 18.4 | ||
| Prices Paid | 43.2 | 58.2 | 38.9 | 0.0 | 58.2 | 62.9 | 67.6 | 17.7 | 4.3 | 63.3 | ||
| Prices Received | 40.1 | 48.1 | 50.8 | 1.1 | 47.0 | 62.1 | 67.9 | 21.9 | 5.0 | 62.9 | ||
| Number of Employees | 9.1 | 21.1 | 69.4 | 9.5 | 11.6 | 30.1 | 32.4 | 50.4 | 7.5 | 24.9 | ||
| Average Employee Workweek | 7.5 | 17.0 | 77.3 | 5.8 | 11.2 | 10.1 | 35.6 | 50.7 | 5.7 | 29.9 | ||
| Capital Expenditures | -- | -- | -- | -- | -- | 34.9 | 26.6 | 56 | 7.8 | 18.9 | ||
| Notes: (1) Diffusion indexes represent the percentage of respondents indicating an increase minus the percentage indicating a decrease. (2) All data are seasonally adjusted. (3) Percentages may not sum to 100 because of rounding, omission by respondents, or both. (4) Survey results reflect data received through November 16, 2026. Federal Reserve Bank of Philadelphia Manufacturing Business Outlook Survey Released: November 19, 2026, at 8:30 a.m. ET. |
||||||||||||