Nonmanufacturing Business Outlook Survey
October 2026 Report
Jump to
Summary of ReturnsView a PDF version of this report | View a TXT version of this report
Nonmanufacturing activity in the region expanded overall this month, according to the firms responding to the October Nonmanufacturing Business Outlook Survey. The indexes for general activity at the firm level, new orders, and sales/revenues all registered positive readings this month. The firms continued to report overall increases in full-time employment, although the index fell this month. The prices paid index moved higher, and the prices received index fell but remained positive. The respondents continue to expect growth at their own firms over the next six months, but expectations were somewhat less widespread.
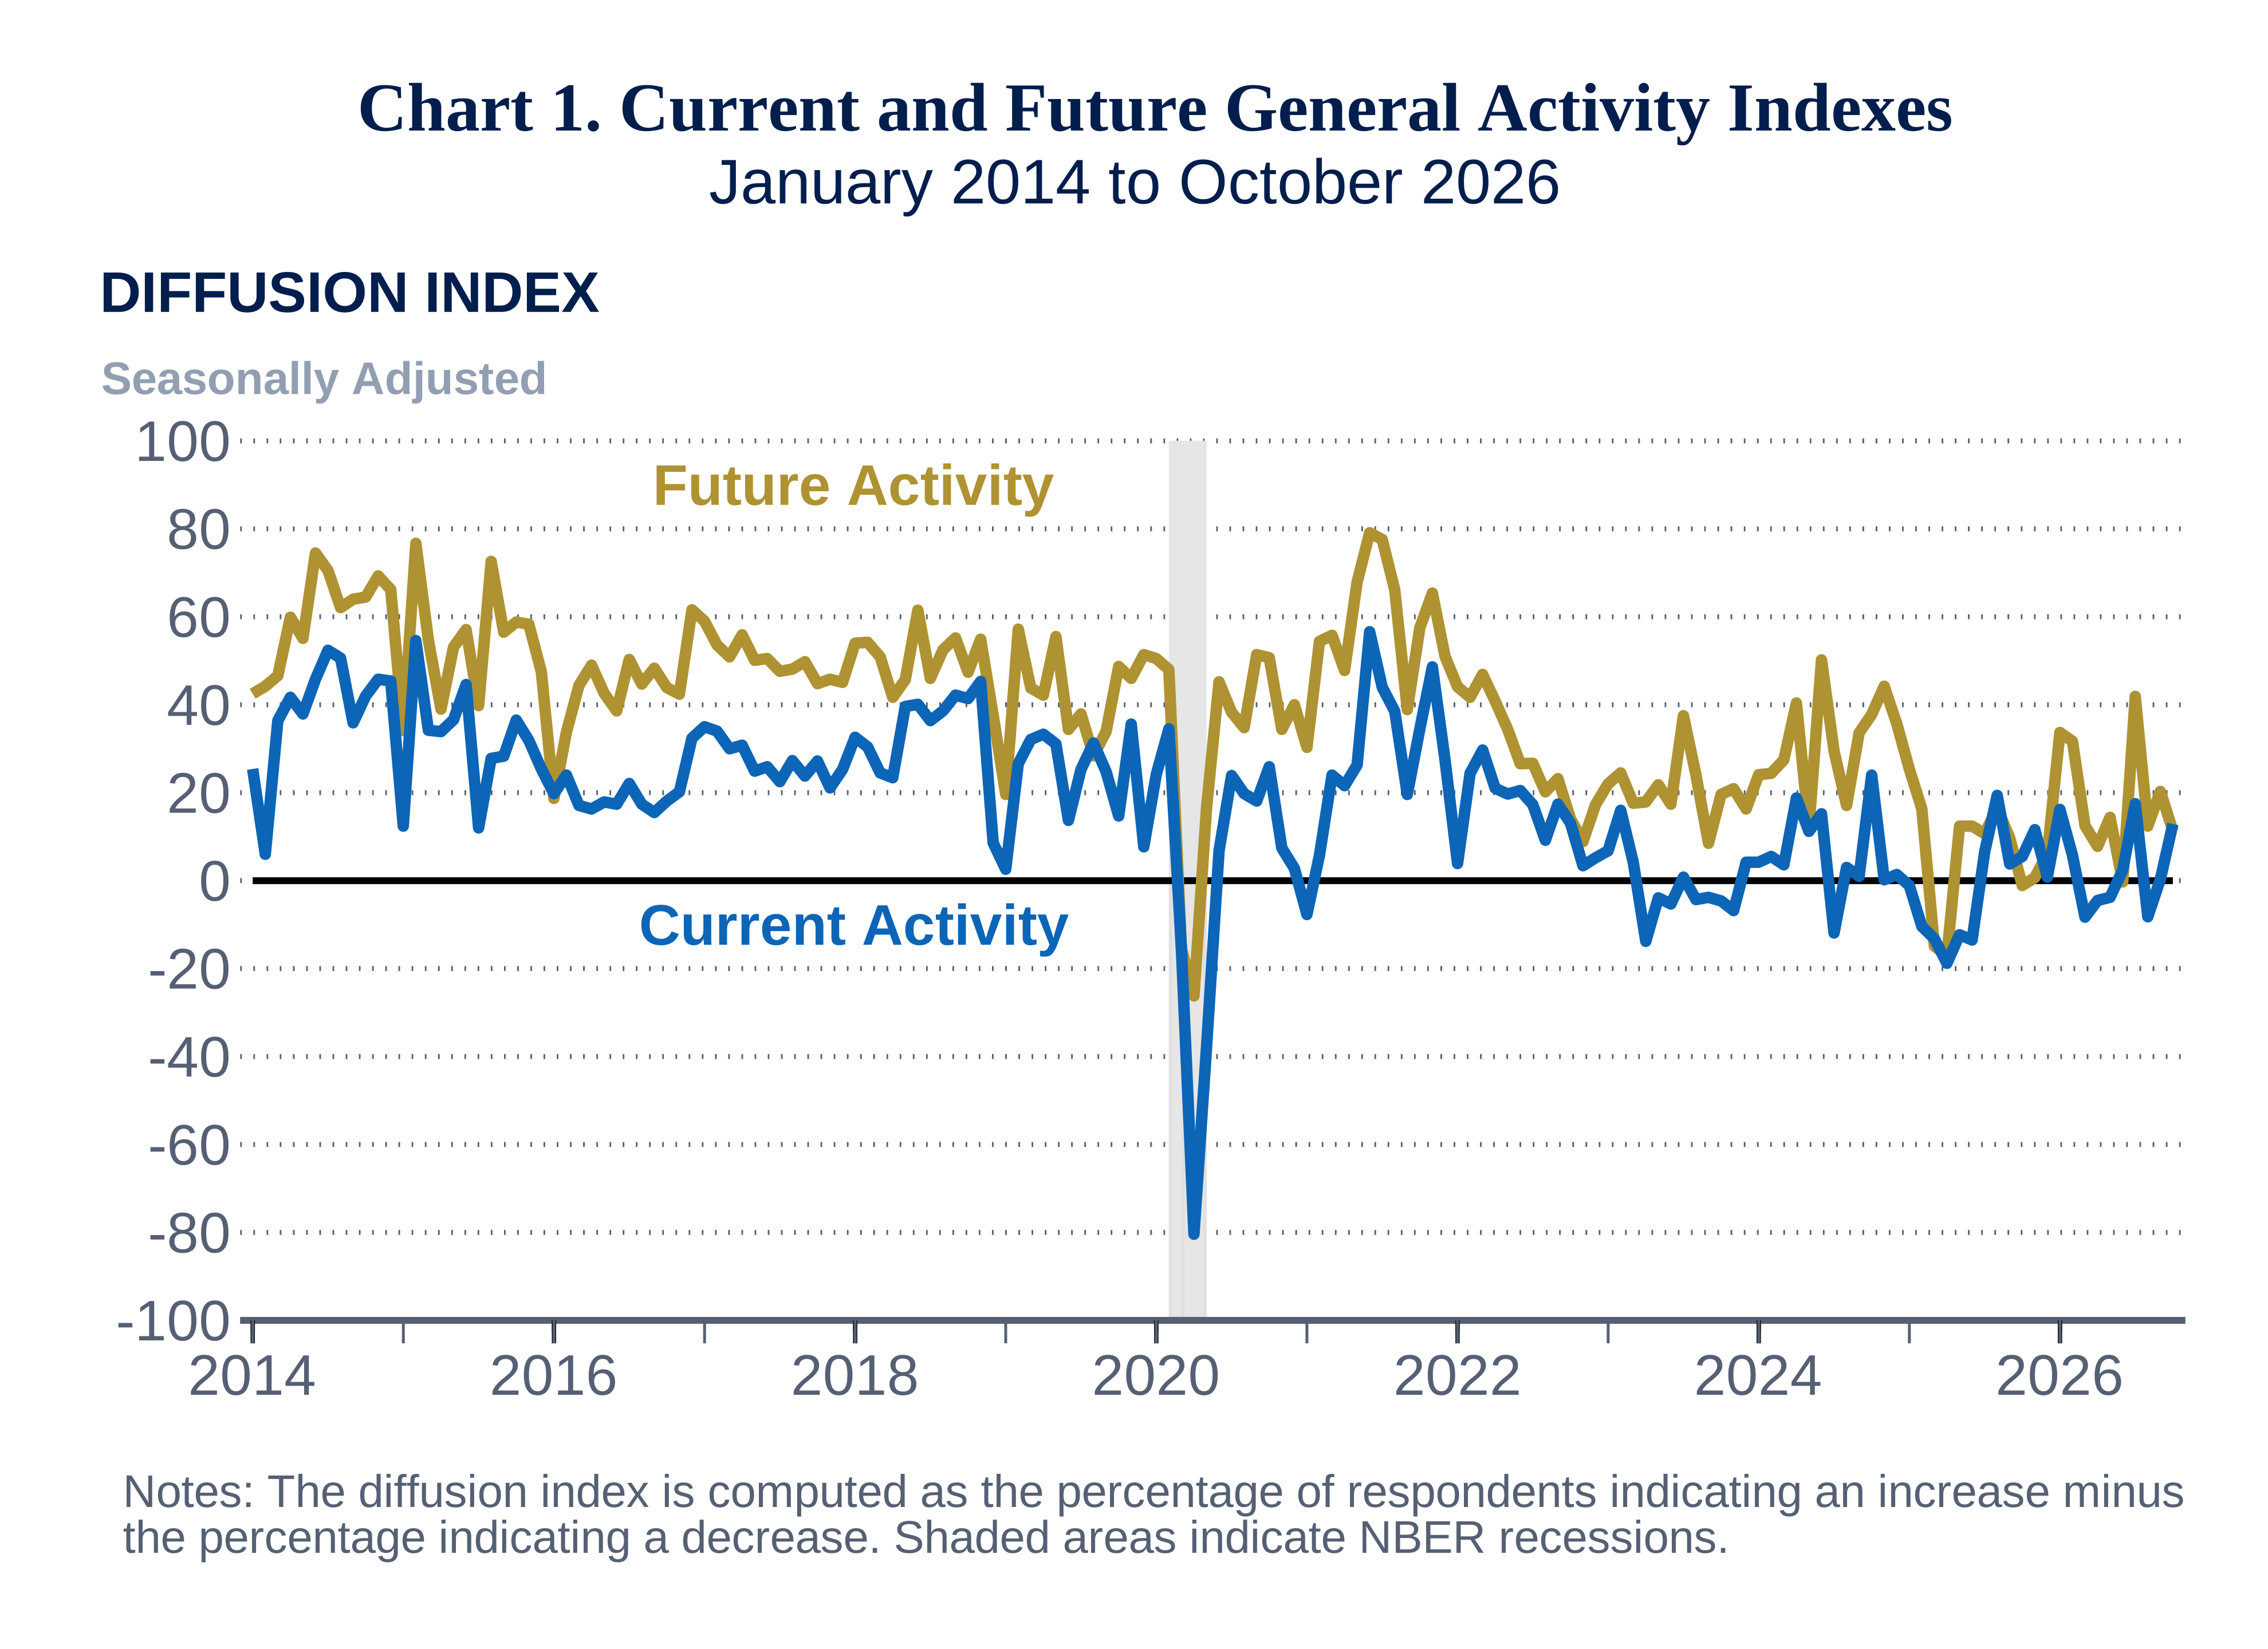
Current Indexes Improve
The diffusion index for current general activity at the firm level rose 13 points to 12.9 this month, its highest reading since July (see Chart 1). More than 38 percent of the firms reported increases in current activity (up from 25 percent last month), 25 percent reported decreases (up slightly from 24 percent), and 37 percent reported no change in activity (down from 45 percent). The new orders index rose from -2.2 to 2.8, recording its first positive reading since July. Almost 25 percent of the firms reported increases in new orders, narrowly exceeding the 22 percent that reported decreases; 22 percent reported no change. The sales/revenues index moved up 8 points to 14.6. Almost 41 percent of the responding firms reported increases in sales/revenues, while 26 percent reported decreases; 31 percent of the firms reported no change. The regional activity index edged down further to -23.6, its lowest reading since June.
Employment Indexes Remain Positive
The full-time employment index declined 7 points to 12.0 this month. Twenty-nine percent of the firms reported increases in full-time employment, 17 percent reported decreases, and 53 percent reported steady employment levels. The part-time employment index fell from 10.7 to 1.3, undoing its increase from last month.
Firms Continue to Report Price Increases
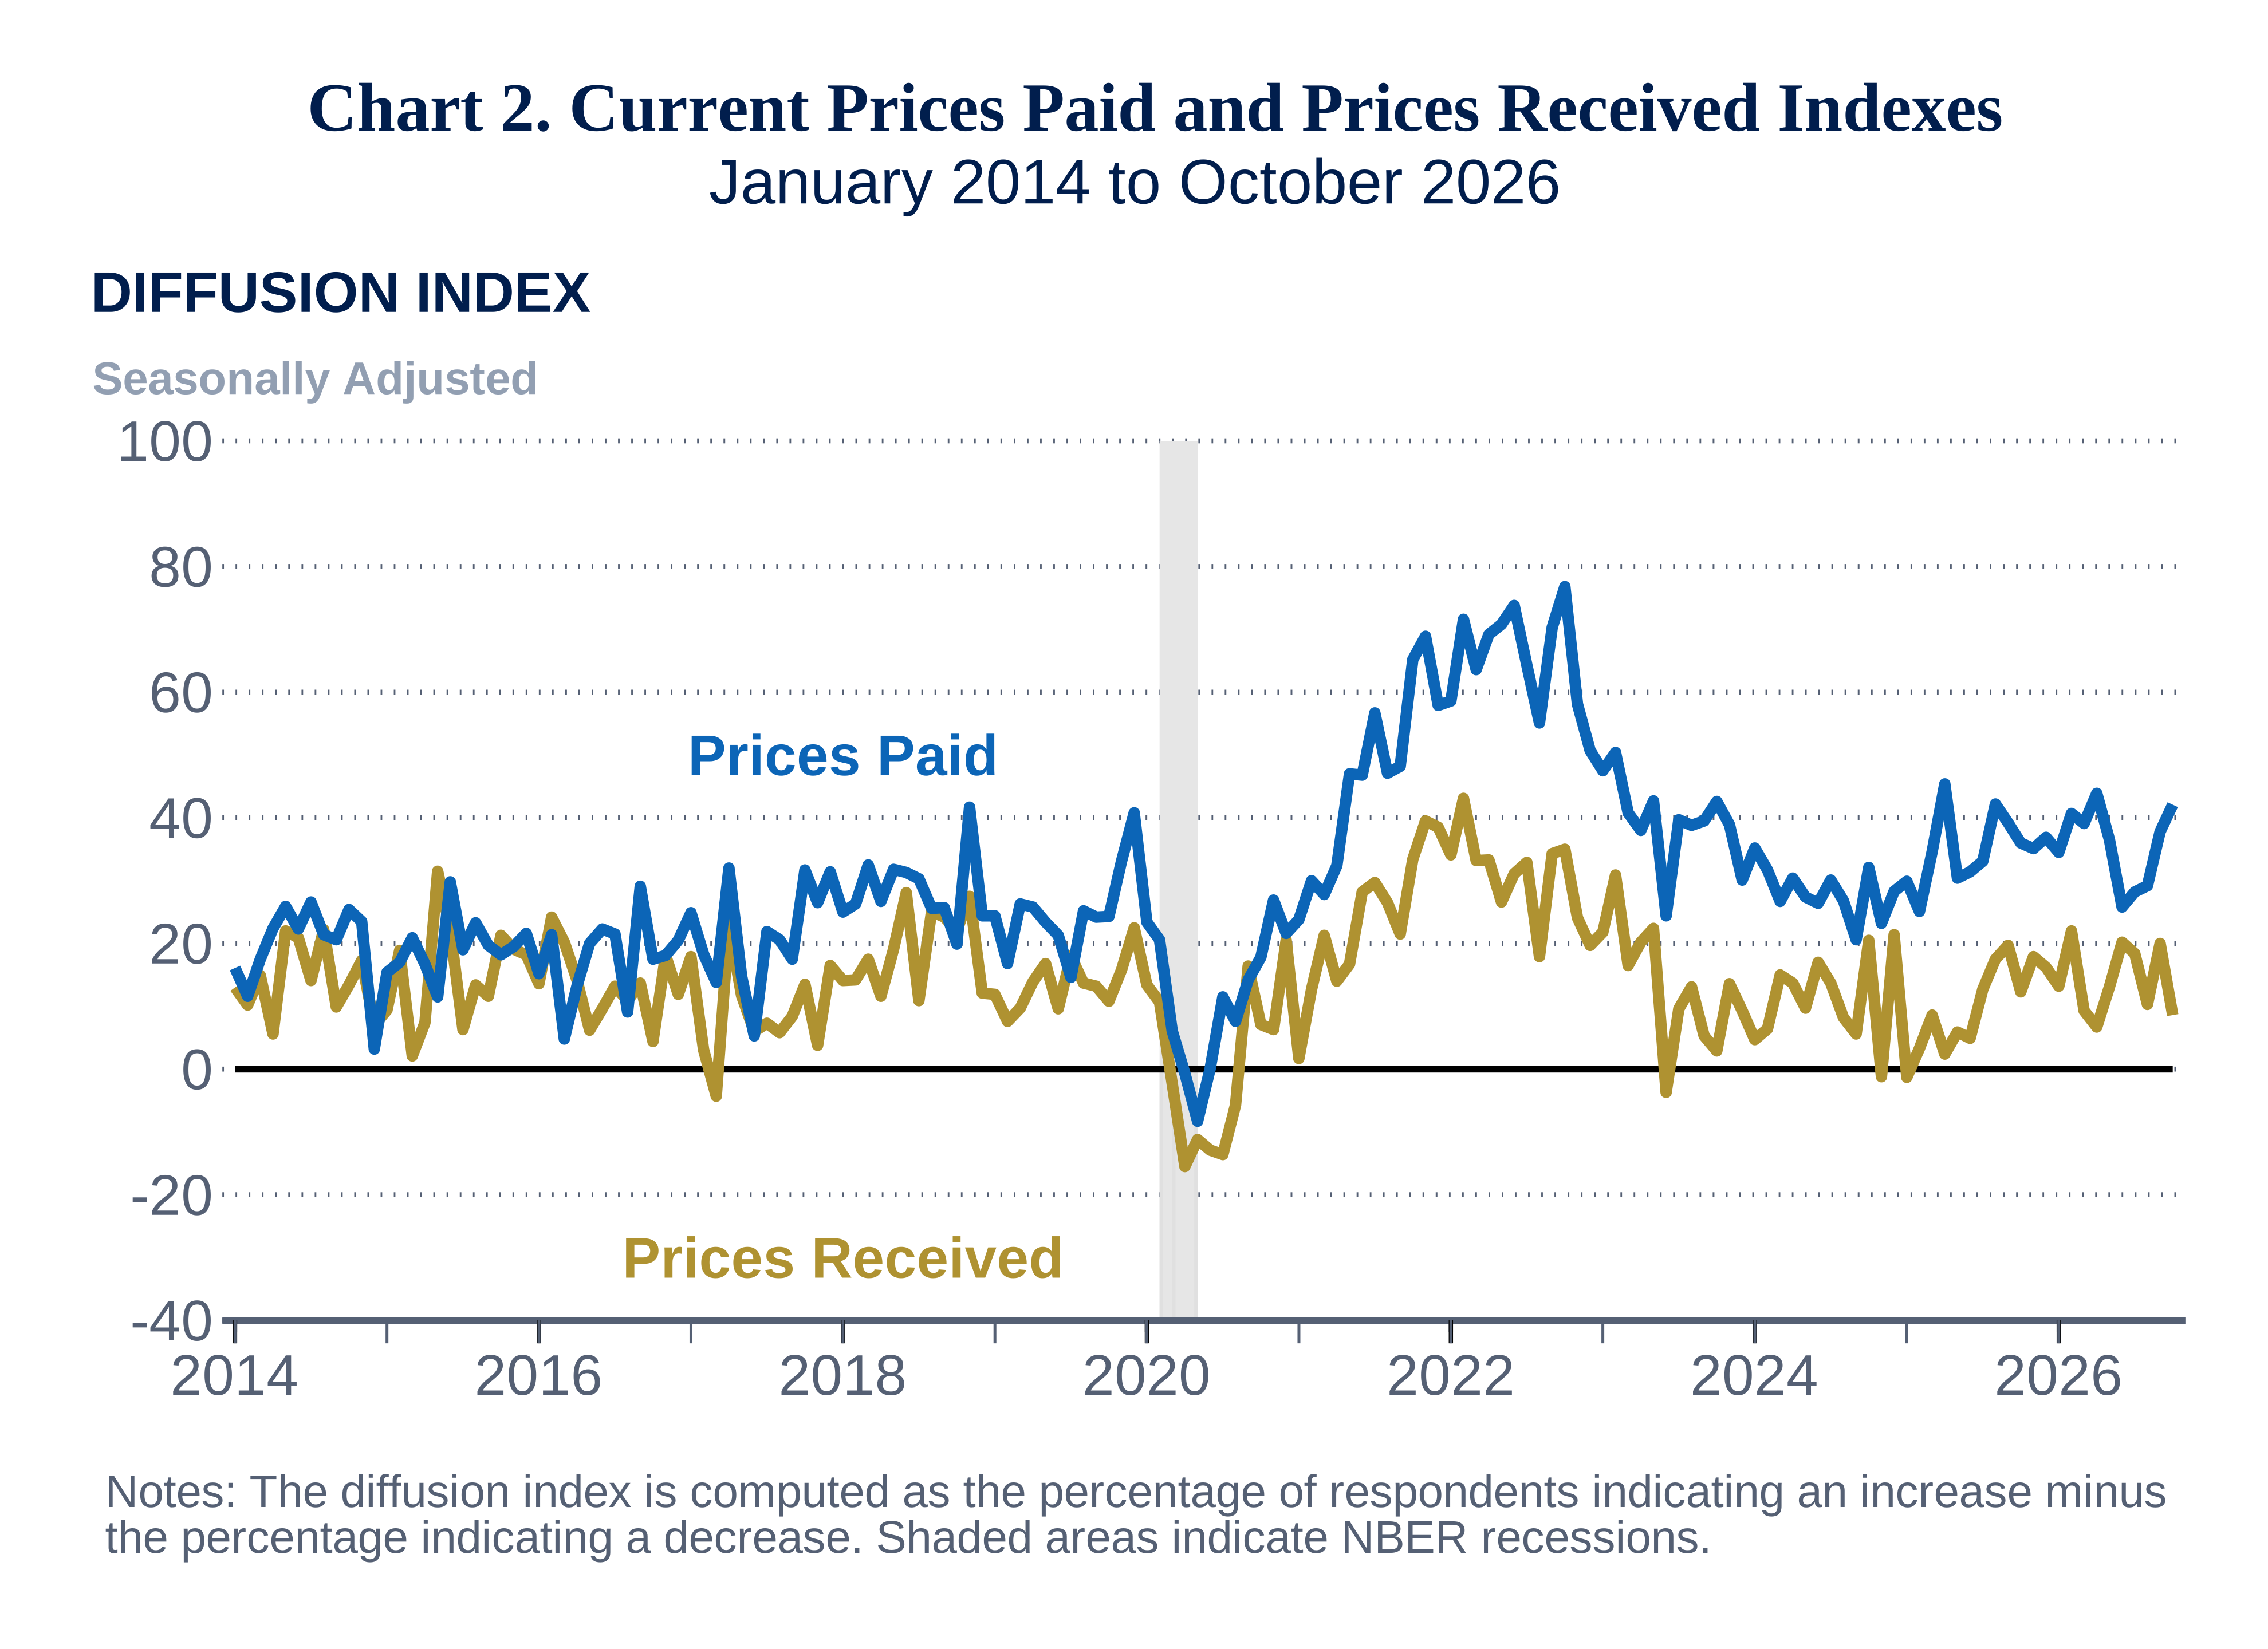
Price indicator readings suggest continued increases in prices for inputs and prices for the firms’ own goods and services. The prices paid index increased 4 points to 42.1, its fourth consecutive increase and highest reading since April (see Chart 2). Almost 50 percent of the respondents reported higher input prices, 33 percent reported no change, and 8 percent reported decreases. Regarding prices for the firms’ own goods and services, the prices received index fell 11 points to 8.6 this month, its lowest reading since April. Almost 18 percent of the firms reported increases in prices received, and 9 percent reported decreases. Most of the firms (67 percent) reported no change in prices for their own goods and services.
Firms Expect Higher Capital Expenditures Overall Next Year
In this month’s special question, nonmanufacturers were asked about their plans for different categories of capital spending for the upcoming year. More than 44 percent of the firms expect to increase their total capital spending next year (up from 39 percent last year), compared with 26 percent expecting to decrease total spending (up from 21 percent); 30 percent expect total spending to stay the same (down from 41 percent). On balance, the firms expect higher capital expenditures next year for software, noncomputer equipment, and computer and related hardware. However, for each of the spending categories, at least 48 percent of the firms expect capital expenditures to stay the same.
Firms Anticipate Growth at Own Firms
The firms’ expectations for future growth were less widespread this month. The diffusion index for future general activity at the firm level fell 9 points to 11.3, its lowest reading since June (see Chart 1). Forty-four percent of the firms expect increases at their firms over the next six months, 33 percent expect decreases, and 23 percent expect no change. The future regional activity index returned to negative territory, moving down 11 points to -9.0 in October.
Summary
Responses to this month’s Nonmanufacturing Business Outlook Survey suggest an overall increase in nonmanufacturing activity among the firms in the region. The indicators for firm-level general activity, new orders, and sales/revenues all rose this month. The employment indexes both moved down this month but continued to suggest overall increases in employment. Both price indexes continued to indicate overall increases in prices, and the prices paid index remained elevated. The firms continued to expect growth at their own firms over the next six months, although these expectations were less widespread.
Special Question (October 2026)
| Comparing 2027 with 2026, do you expect capital expenditures to be higher, the same, or lower for each of the following categories? | ||||
|---|---|---|---|---|
|
Higher (% of reporters) |
Same (% of reporters) |
Lower (% of reporters) |
Diffusion Index |
|
| Software | 37.9 | 48.3 | 13.8 | 24.1 |
| Noncomputer equipment | 31.0 | 48.3 | 20.7 | 10.3 |
| Energy-saving investments | 17.4 | 56.5 | 26.1 | -8.7 |
| Computer and related hardware | 27.6 | 55.2 | 17.2 | 10.3 |
| Structure | 14.3 | 57.1 | 28.6 | -14.3 |
| Other | 25.0 | 66.7 | 8.3 | 16.7 |
| Total capital spending | 44.4 | 29.6 | 25.9 | 18.5 |
NBOS Summary of Returns – October 2026
| October vs. September | |||||||
|---|---|---|---|---|---|---|---|
|
Previous Diffusion Index |
Increase | No change | Decrease |
Diffusion Index |
|||
| What is your assessment of general business activity for the region? | -22.0 | 10.9 | 54.7 | 34.5 | -23.6 | ||
| What is your assessment of general business activity for your firm? | 0.3 | 38.2 | 36.6 | 25.3 | 12.9 | ||
| Company Business Indicators | |||||||
| New Orders | -2.2 | 24.6 | 22.4 | 21.8 | 2.8 | ||
| Sales or Revenues | 6.8 | 40.9 | 30.5 | 26.3 | 14.6 | ||
| Unfilled Orders | -7.1 | 7.1 | 16.9 | 14.1 | -7.0 | ||
| Inventories | -9.3 | 7.5 | 8.8 | 13.0 | -5.5 | ||
| Prices Paid | 37.8 | 49.6 | 33.0 | 7.5 | 42.1 | ||
| Prices Received | 20.0 | 17.6 | 66.8 | 9.0 | 8.6 | ||
| Number of Employees – Full-Time Permanent | 19.0 | 29.0 | 53.4 | 17.0 | 12.0 | ||
| Number of Employees – Part-Time, Temporary, and Contract | 10.7 | 13.9 | 65.3 | 12.7 | 1.3 | ||
| Average Employee Workweek | 8.5 | 21.8 | 67.4 | 10.5 | 11.3 | ||
| Wage and Benefit Costs | 40.7 | 51.3 | 43.7 | 2.7 | 48.5 | ||
| Capital Expenditures – Physical Plant | 22.9 | 23.5 | 30.7 | 10.5 | 13.0 | ||
| Capital Expenditures – Equipment and Software | 33.0 | 30.5 | 36.4 | 11.6 | 18.9 | ||
| Six Months from Now vs. October | |||||||
|
Previous Diffusion Index |
Increase | No change | Decrease |
Diffusion Index |
|||
| What is your assessment of general business activity for the region? | 2.0 | 26.1 | 37.8 | 35.1 | -9.0 | ||
| What is your assessment of general business activity for your firm? | 20.3 | 44.0 | 23.2 | 32.8 | 11.3 | ||
| Notes: (1) Diffusion indexes represent the percentage of respondents indicating an increase minus the percentage indicating a decrease. (2) All data are seasonally adjusted. (3) Percentages may not sum to 100 because of rounding, omission by respondents, or both. (4) Survey results reflect data received through October 15, 2026. Federal Reserve Bank of Philadelphia Nonmanufacturing Business Outlook Survey Released: October 20, 2026, at 8:30 a.m. ET. |
|||||||