Nonmanufacturing Business Outlook Survey
September 2026 Report
Note: Survey responses were collected from September 7 to September 17.
Jump to
Summary of ReturnsView a PDF version of this report | View a TXT version of this report
Nonmanufacturing activity in the region on balance was mostly steady this month, according to the firms responding to the September Nonmanufacturing Business Outlook Survey. The index for general activity at the firm level rose to a near-zero reading this month, while the new orders index remained negative and the sales/revenues index remained positive. Increases in both full- and part-time employment were more widespread compared with last month. Both price indexes rose and continued to indicate overall increases in prices. The firms continued to expect growth over the next months, and both future activity indexes rose.
Current Indexes Are Mixed
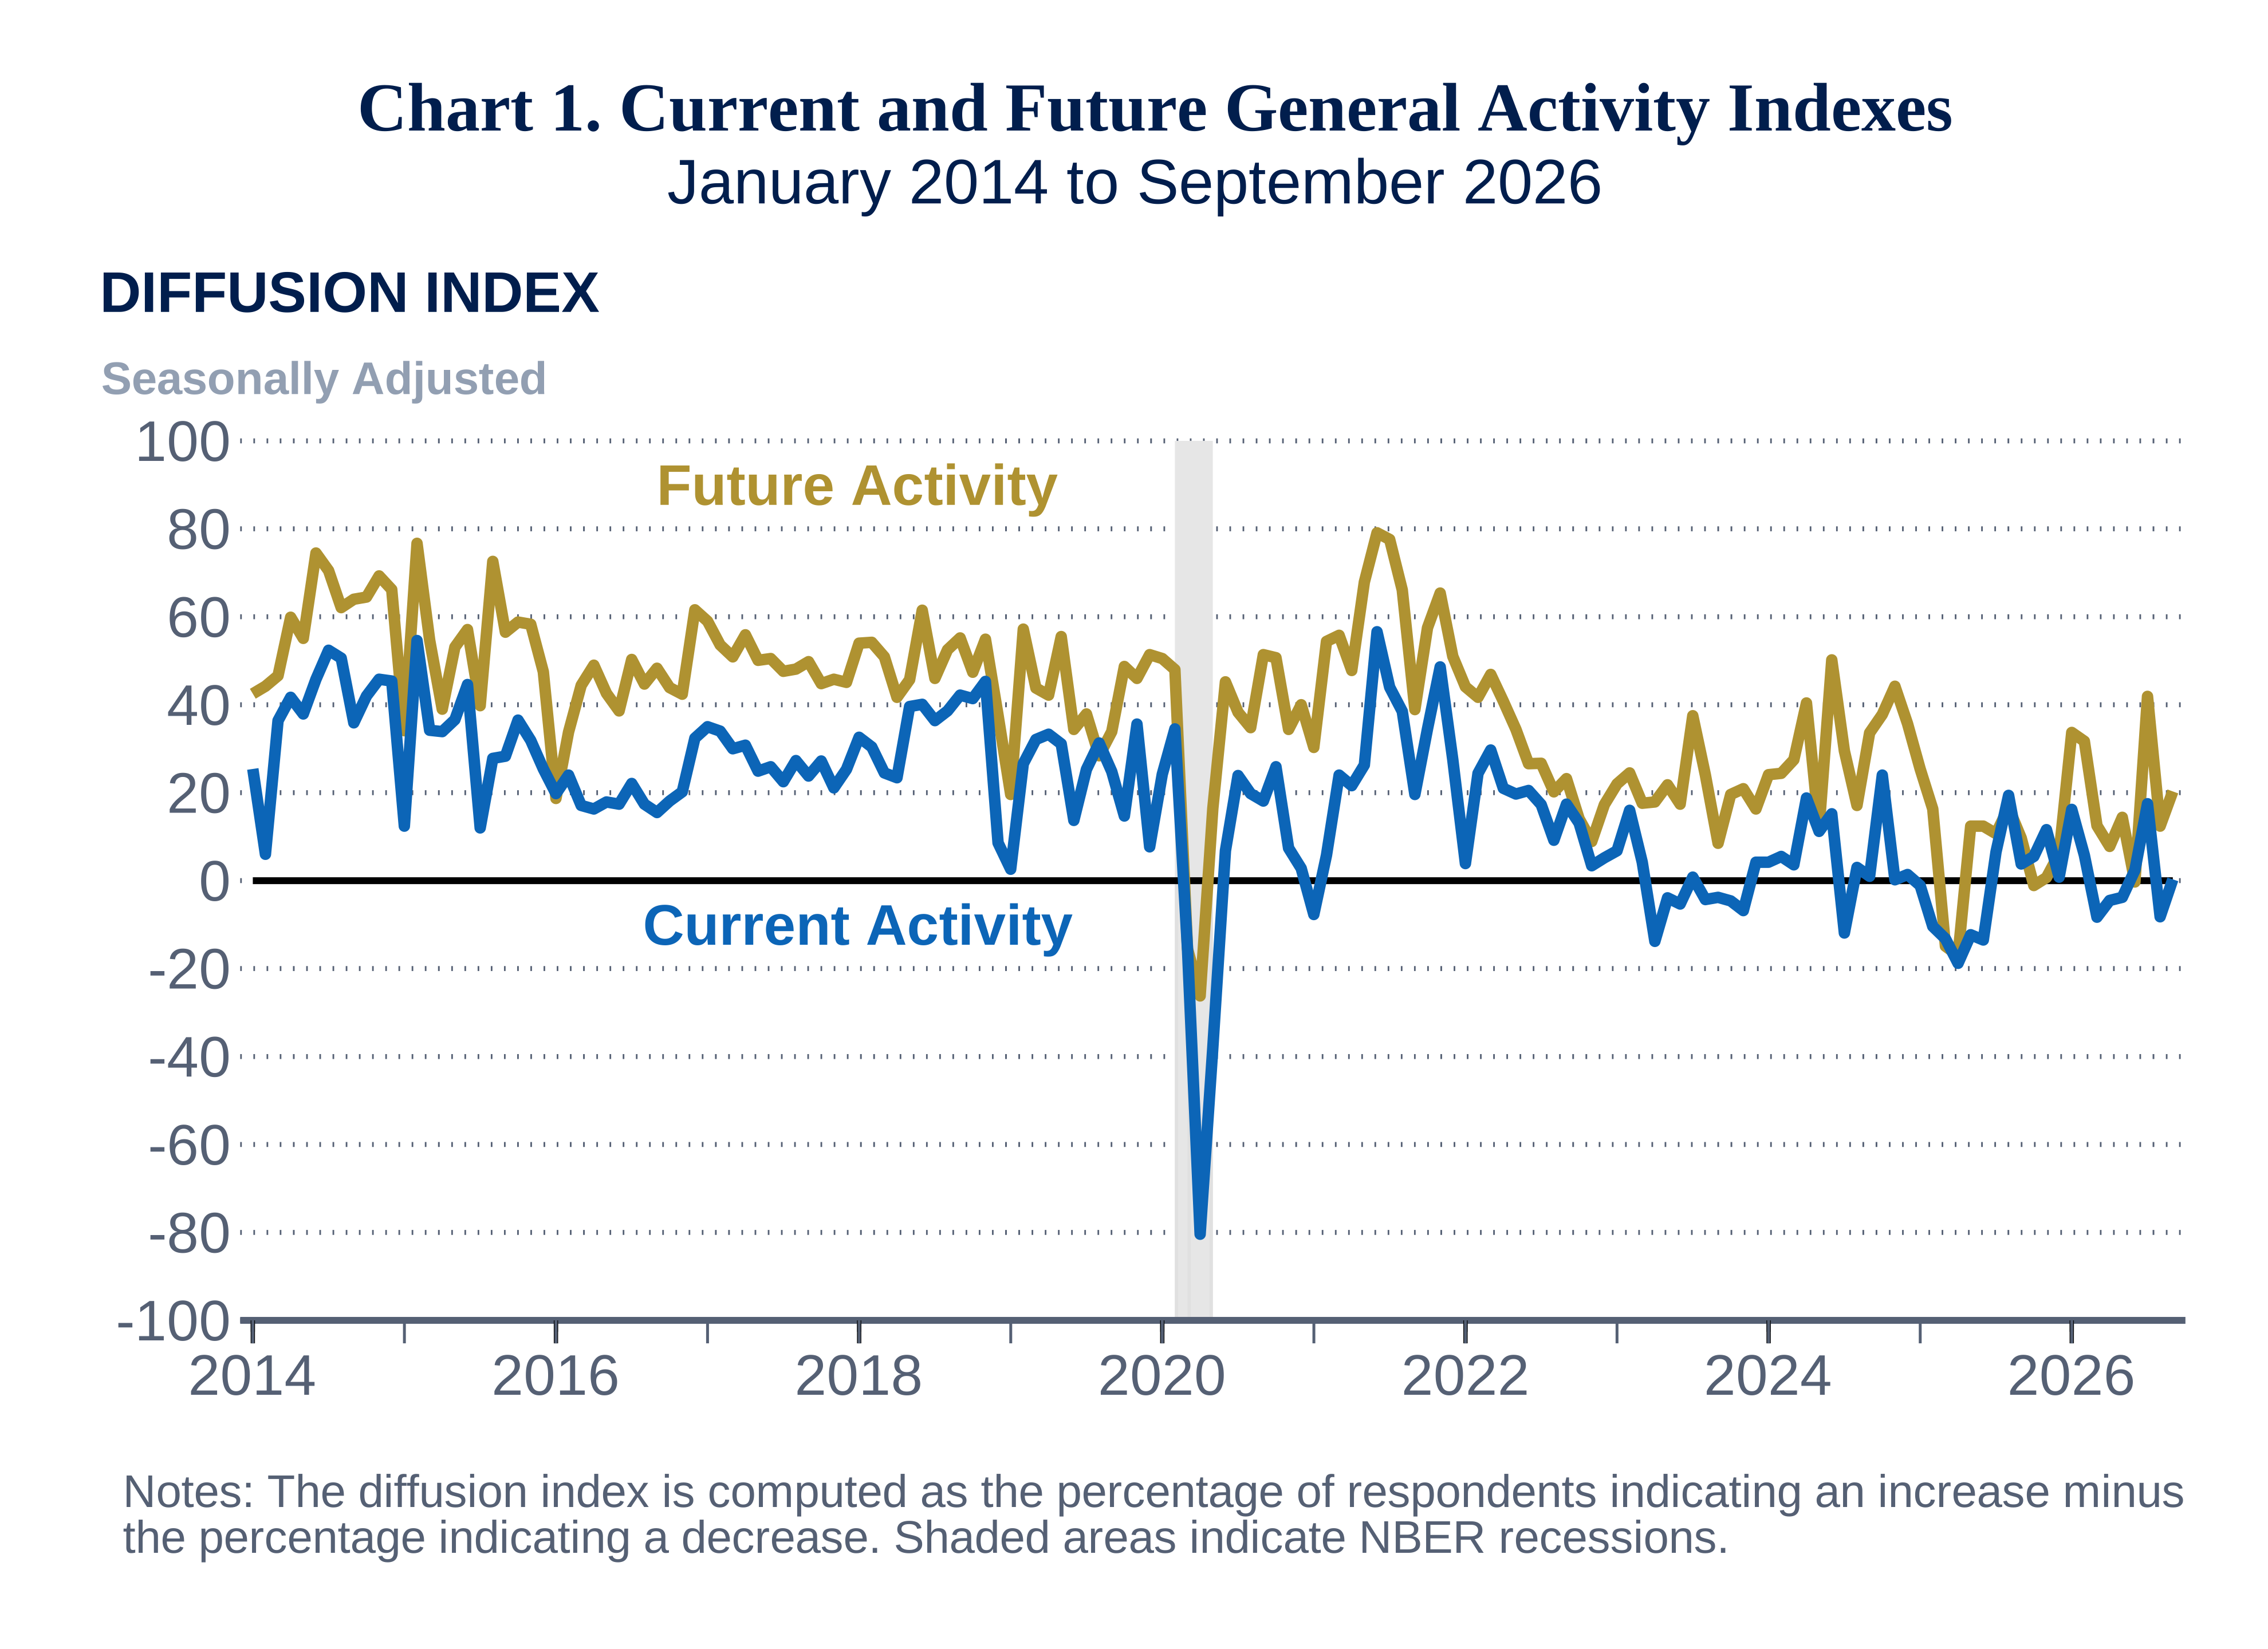
The diffusion index for current general activity at the firm level rose 9 points to 0.3 this month (see Chart 1). Almost 25 percent of the firms reported increases in current activity (up from 17 percent last month), 24 percent reported decreases (down from 26 percent), and 45 percent reported no change in activity (down from 49 percent). The new orders index rose from -10.1 to -2.2, its seventh negative reading in the past eight months. More than 17 percent of the firms reported decreases in new orders, narrowly exceeding the 15 percent that reported increases; 41 percent reported no change. The sales/revenues index edged down 1 point to 6.8. More than 28 percent of the responding firms reported increases in sales/revenues, while 21 percent reported decreases; 44 percent of the firms reported no change. The regional activity index fell further into negative territory to -22.0 this month, its lowest reading since June.
Employment Indexes Improve
The full-time employment index rose 17 points to 19.0 this month, its highest reading since June 2022. Almost 27 percent of the firms reported increases in full-time employment (up from 14 percent last month), 8 percent reported decreases (down from 12 percent), and 64 percent reported steady employment levels (down from 69 percent). The part-time employment index also increased, rising 10 points to 10.7.
Firms Continue to Report Price Increases
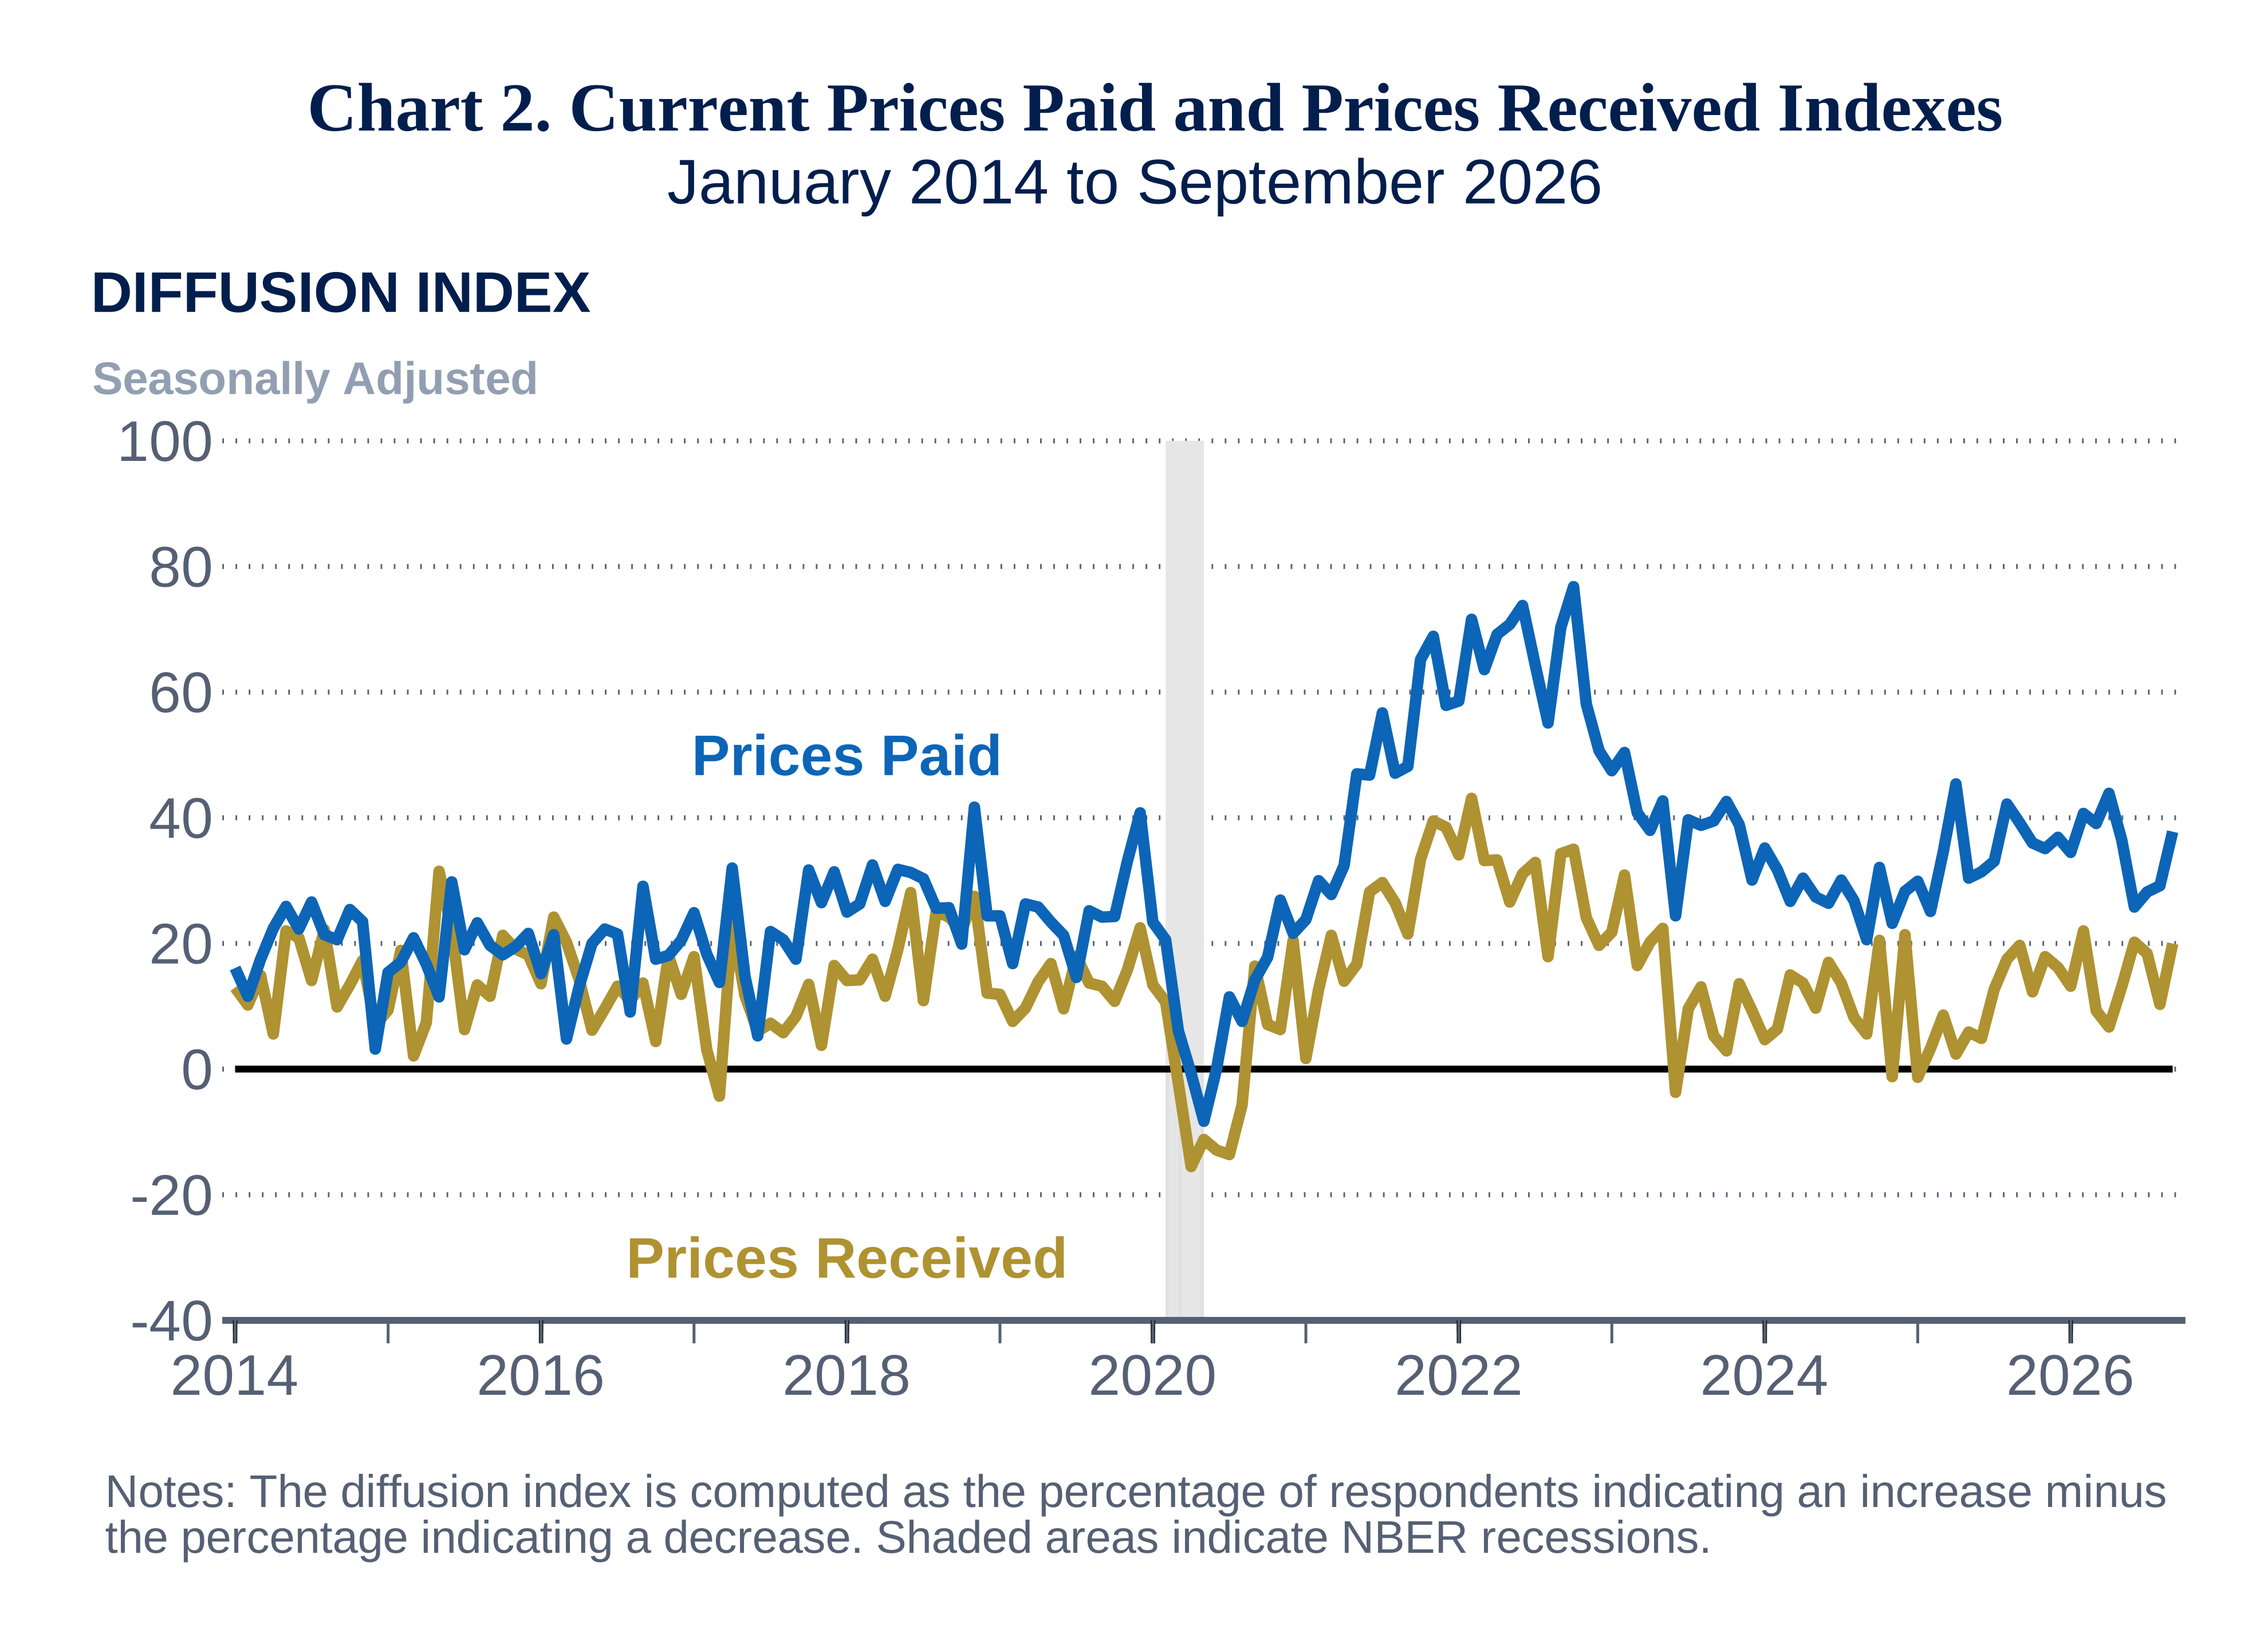
Price indicator readings suggest continued increases in prices for inputs and prices for the firms’ own goods and services. The prices paid index increased 9 points to 37.8 (see Chart 2). More than 40 percent of the respondents reported higher input prices, 46 percent reported no change, and 3 percent reported decreases. Regarding prices for the firms’ own goods and services, the prices received index rose 10 points to 20.0 this month, its highest reading since June. Almost 23 percent of the firms reported increases in prices received, and 3 percent reported decreases. Most of the firms (69 percent) reported no change in prices for their own goods and services.
Firms Report Higher Sales/Revenues on Balance
In this month’s special questions, the firms were asked to estimate their total sales/revenues growth for the third quarter ending this month compared with the second quarter of 2026; they were also asked about factors constraining business operations. Almost 55 percent of the firms reported expected increases in third-quarter sales/revenues, while 24 percent reported expected decreases. In the current quarter, more than 79 percent of the firms reported uncertainty as at least a slight constraint, down slightly from 82 percent last quarter. Further, almost 63 percent of the firms cited energy markets as at least a slight constraint (down from 83 percent), and 61 percent of the firms indicated labor supply as at least a slight constraint (little changed). Looking ahead over the next three months, a majority of the firms expect the impacts of energy markets and uncertainty to worsen and for labor supply impacts to stay the same.
Firms Anticipate Growth at Own Firms
The firms’ expectations for future growth were more widespread this month. The diffusion index for future general activity at the firm level rose 8 points to 20.3, partially recovering some of its sharp decline last month (see Chart 1). Almost 44 percent of the firms expect increases at their firms over the next six months, 24 percent expect decreases, and 32 percent expect no change. The future regional activity index moved up 8 points to 2.0 in September.
Summary
Responses to this month’s Nonmanufacturing Business Outlook Survey suggest mostly steady nonmanufacturing activity among the firms in the region. The indicators for firm-level general activity rose to a near-zero reading, the new orders index rose but remained negative, and the sales/revenues index remained positive. The full- and part-time employment indexes increased this month. Both price indexes moved up and continued to indicate overall increases in prices. The firms continue to expect growth at their own firms over the next six months.
Special Questions (September 2026)
| An increase of: | % of firms | Subtotals |
|---|---|---|
| 10% or more | 15.2 | % of firms reporting an increase: 54.6 |
| 5-10% | 6.1 | |
| 0-5% | 33.3 | |
| No change | 21.2 | |
| A decline of: | ||
| 0-5% | 12.0 | % of firms reporting a decrease: 24.2 |
| 5-10% | 6.1 | |
| 10% or more | 6.1 |
|
Not at all (%) |
Slightly (%) |
Moderately (%) |
Significantly (%) |
|
|---|---|---|---|---|
| Energy markets | 37.5 | 25.0 | 21.9 | 15.6 |
| Financial capital | 58.6 | 20.7 | 17.2 | 3.4 |
| Labor supply | 38.7 | 35.5 | 16.1 | 9.7 |
| Supply chains | 50.0 | 28.6 | 14.3 | 7.1 |
| Uncertainty | 20.6 | 23.5 | 26.5 | 29.4 |
| Other factors | 58.8 | 17.6 | 11.8 | 11.8 |
|
Worsen (%) |
Stay the same (%) |
Improve (%) |
|
|---|---|---|---|
| Energy markets | 57.1 | 34.3 | 8.6 |
| Financial capital | 34.5 | 65.5 | 0.0 |
| Labor supply | 20.0 | 74.3 | 5.7 |
| Supply chains | 32.1 | 60.7 | 7.1 |
| Uncertainty | 52.9 | 41.2 | 5.9 |
| Other factors | 20.0 | 73.3 | 6.7 |
NBOS Summary of Returns – September 2026
| September vs. August | |||||||
|---|---|---|---|---|---|---|---|
|
Previous Diffusion Index |
Increase | No change | Decrease |
Diffusion Index |
|||
| What is your assessment of general business activity for the region? | -10.6 | 9.7 | 54.4 | 31.7 | -22.0 | ||
| What is your assessment of general business activity for your firm? | -8.2 | 24.5 | 45.1 | 24.2 | 0.3 | ||
| Company Business Indicators | |||||||
| New Orders | -10.1 | 15.1 | 40.8 | 17.3 | -2.2 | ||
| Sales or Revenues | 7.9 | 28.1 | 43.6 | 21.3 | 6.8 | ||
| Unfilled Orders | -12.7 | 6.7 | 25.9 | 13.7 | -7.1 | ||
| Inventories | -1.1 | 0.0 | 24.4 | 9.3 | -9.3 | ||
| Prices Paid | 29.2 | 40.8 | 45.9 | 3.0 | 37.8 | ||
| Prices Received | 10.3 | 22.8 | 69.0 | 2.8 | 20.0 | ||
| Number of Employees – Full-Time Permanent | 2.1 | 26.8 | 63.7 | 7.8 | 19.0 | ||
| Number of Employees – Part-Time, Temporary, and Contract | 1.1 | 18.5 | 62.5 | 7.8 | 10.7 | ||
| Average Employee Workweek | -13.4 | 15.8 | 72.6 | 7.3 | 8.5 | ||
| Wage and Benefit Costs | 39.2 | 45.0 | 47.0 | 4.3 | 40.7 | ||
| Capital Expenditures – Physical Plant | -0.6 | 28.2 | 30.1 | 5.3 | 22.9 | ||
| Capital Expenditures – Equipment and Software | 8.8 | 40.0 | 44.0 | 7.0 | 33.0 | ||
| Six Months from Now vs. September | |||||||
|
Previous Diffusion Index |
Increase | No change | Decrease |
Diffusion Index |
|||
| What is your assessment of general business activity for the region? | -6.3 | 30.5 | 39.9 | 28.4 | 2.0 | ||
| What is your assessment of general business activity for your firm? | 12.4 | 43.8 | 31.8 | 23.5 | 20.3 | ||
| Notes: (1) Diffusion indexes represent the percentage of respondents indicating an increase minus the percentage indicating a decrease. (2) All data are seasonally adjusted. (3) Percentages may not sum to 100 because of rounding, omission by respondents, or both. (4) Survey results reflect data received through September 17, 2026. Federal Reserve Bank of Philadelphia Nonmanufacturing Business Outlook Survey Released: September 22, 2026, at 8:30 a.m. ET. |
|||||||